7 best payment gateways in Singapore (2026 guide)

Cherie Foo
Growth Content Manager

Key Takeaways:
The right payment gateway in Singapore affects your checkout conversion, total transaction costs, and how easily you collect revenue across markets.
For businesses scaling beyond Singapore, what separates gateways is settlement currency breadth, local payment method coverage by market, and platform breadth.
Airwallex supports 160+ local payment methods and combines online payments with in-person payments through Airwallex POS, helping businesses accept payments across both digital and physical channels.
Choosing a payment gateway in Singapore? You’re in the right place.
This guide compares seven payment gateways used by Singapore businesses: Airwallex, PayPal, Stripe, Adyen, Shopify Payments, HitPay, and Opn Payments. For each, we cover fees, supported payment methods, settlement coverage, and the kind of business it actually suits.
You'll find a side-by-side comparison table, deeper per-provider analysis, and a decision framework to help you choose based on your needs and situation.
7 best payment gateways in Singapore (2026)
The right gateway for you depends on your order mix, your cross-border exposure, and how broad a platform you need. Here’s a quick overview of the seven providers to choose from:
Provider | Domestic card fees | International card fees | Like-for-like settlement | Payment methods |
|---|---|---|---|---|
Airwallex | 3.30% + S$0.50 | 3.60% + S$0.50 |
| 160+ |
PayPal1 | 3.40% + S$0.50 | 4.10% + S$0.50 |
| Coverage not stated |
Stripe² | 3.4% + S$0.50 | 3.9% + S$0.50 (+2% FX if applicable) | ⚠️ Separate bank accounts needed* | 100+ |
Adyen3 | €0.11 + Interchange++ + 0.60% | €0.11 + Interchange++ + 0.60% |
| 200+ |
Shopify Payments⁴ | From 3.2% + S$0.50 | From 3.6% + S$0.50 |
| Coverage not stated |
HitPay⁵ | 2.8% + S$0.50 | 3.65% + S$0.50 (+2% FX) |
| 700+ |
Opn Payments (Omise)⁶ | 3.30% + S$0.30 | Not stated |
| Coverage not stated |


This information is based on publicly available information accessed on 11 Sep 2026. Information reflects Airwallex's own research and has not been independently verified.
*Stripe does support multi-currency settlement in Singapore; however, you need a separate supported bank account for each settlement currency you configure. Stripe charges a 1% fee when funds settle into a non-primary settlement currency.2
1. Airwallex
Airwallex is particularly well suited to businesses expanding across markets and selling through multiple channels.
It combines online payments with in-person payments through Airwallex POS, so businesses can manage both digital and physical sales through the same payment platform. It also offers Optimize 360, which helps businesses optimise payment performance across their payment setup and acquiring connections.
Features:
Online payment acceptance with 160+ local payment methods across 180+ countries
Airwallex POS for in-person payments
Like-for-like settlement in 14 currencies
Local acquiring in supported markets
Multi-currency Global Accounts for collecting and holding funds
Airwallex is a strong fit for businesses that sell internationally and need payment acceptance across both online and physical channels.
2. PayPal
PayPal is particularly well suited to businesses selling internationally, especially those that want to offer customers a familiar checkout option without building a payment experience from scratch.
Its strong consumer recognition can be useful for B2C businesses selling to customers across different markets, where shoppers may already have a PayPal account and prefer to pay through a service they know.
Features:
PayPal checkout for online payments
PayPal and major card payment acceptance
Support for payments from customers in multiple countries
PayPal Wallet, allowing customers to pay using stored payment methods
Express checkout options designed to reduce checkout steps
Seller protection for eligible transactions
Payment processing and transaction management through PayPal Business
For more information, read our PayPal Business Account review.
Information in this section is based on PayPal’s official website as of 11 Sep 2026.
3. Stripe
Stripe is particularly well suited to SaaS companies, digital businesses, and teams with developer resources that want a highly customisable payment setup.
Its strength is the flexibility of its APIs and developer tooling, making it easier to build payments into websites, apps, and other digital products rather than relying on a fixed checkout experience.
Features:
Online payment acceptance for cards and local payment methods
Payment Links and hosted checkout options
Support for subscriptions and recurring payments
Stripe Billing for subscription and invoicing workflows
Stripe Connect for marketplaces and platforms
Stripe Radar for fraud detection and prevention
APIs and developer tools for custom payment integrations
Information in this section is based on Stripe’s official website as of 11 Sep 2026.
4. Adyen
Adyen is particularly well suited to larger businesses that need to manage high-volume payments across multiple markets and sales channels.
Its strength is bringing online and in-person payments into one platform, with a strong focus on global acquiring, payment optimisation, and unified commerce.
Features:
Online and in-person payment acceptance
200+ payment methods
Unified Commerce for connecting online and offline payment data
Local acquiring across multiple markets
Interchange++ card pricing
Adyen for Platforms for marketplaces and platforms
Risk management and fraud prevention through RevenueProtect
Information in this section is based on Adyen’s official website as of 11 Sep 2026.
5. Shopify Payments
Shopify Payments is only available to businesses that use Shopify, so it makes sense primarily for merchants that want payment processing built directly into their Shopify store.
Its main advantage is simplicity: merchants can manage payments alongside their products, orders, customers, and other Shopify operations without adding a separate payment gateway.
Features:
Native payment processing within Shopify
Online card payments and supported local payment methods
Shop Pay accelerated checkout
Apple Pay and Google Pay support
Fraud analysis and payment protection tools
Automatic payment and order reconciliation within Shopify
Support for multiple currencies and international sales
For more information, read our Shopify Payments guide.
Information in this section is based on Shopify’s official website as of 11 Sep 2026.
6. HitPay
HitPay is a Singapore-based payment platform aimed particularly at small and growing businesses.
Its strength is making it easy for local merchants to accept a broad range of payment methods without needing a complex payment setup, making it a practical option for businesses whose customers are primarily in Singapore.
Features:
Online payment acceptance
PayNow and other Singapore payment methods
Cards and digital wallets
Payment Links for accepting payments without a full online checkout
In-person payments through supported hardware and payment options
Invoicing and payment collection tools
Integrations with eCommerce platforms and other business tools
Information in this section is based on HitPay’s official website as of 11 Sep 2026.
7. Opn Payments (Omise)
Opn Payments / Omise is particularly suited to businesses that want to reach customers across Southeast Asia and offer locally familiar payment methods.
Its regional coverage is the main draw, making it useful for merchants whose customer base spans markets with different wallets and payment preferences.
Features:
Online payment acceptance across Southeast Asia
Cards and local payment methods
Regional wallets including Alipay+, GCash, Dana, KakaoPay, and Touch 'n Go
PayNow for Singapore customers
Payment Links for collecting payments without a full checkout integration
Recurring and subscription payments
APIs and plugins for integrating payments into websites and apps
Information in this section is based on Opn’s official website as of 11 Sep 2026.
How to choose the right payment gateway for your business
The right payment gateway depends less on the headline transaction rate and more on how you sell, where your customers are, and what happens after you collect the money.
Here’s a quick overview:
What to consider | Why it matters |
|---|---|
Where you sell | International sales can make settlement currencies, FX, and local acquiring more important than domestic card rates. |
How customers pay | Your gateway needs to support the cards, wallets, and local payment methods your customers actually use. |
Online and in-person sales | If you sell through multiple channels, a gateway that connects online and offline payments can simplify operations. |
What happens after payment | Businesses with international revenue may also need multi-currency accounts, supplier payments, cards, or expense management. |
How you want to manage payments | Larger or more complex businesses may benefit from features such as payment routing, fraud tools, and marketplace capabilities. |
Your pricing model | Compare the full cost of your actual transaction mix, including payment-method fees, FX, settlement, and any minimums or subscriptions. |
Where do you sell?
If most of your sales are in Singapore, domestic card acceptance and local payment methods may be your biggest priorities.
If you sell internationally, look at whether the provider supports the currencies and markets you care about, how funds are settled, and whether local acquiring is available.
Which payment methods do your customers use?
Don't choose a gateway based solely on the number of payment methods it advertises. Check whether it supports the specific methods your customers use in each market.
For Singapore, that could include PayNow, cards, GrabPay, and other wallets. If you sell across Southeast Asia, you may also need market-specific methods such as GCash in the Philippines, DANA in Indonesia, or Touch 'n Go in Malaysia.
Do you sell both online and in person?
If you operate a physical store as well as an online business, check whether the provider supports both channels and whether the payments can be managed from the same platform.
This can reduce the need to run separate payment systems and give you a more consistent view of transactions across your business.
Do you need more than payment acceptance?
A payment gateway handles accepting customer payments. Some platforms go further with products such as multi-currency business accounts, international transfers, corporate cards, expense management, or bill payments.
If your business regularly collects money in one currency and pays suppliers or staff in another, these capabilities may be worth considering alongside payment acceptance.
How complex are your payment operations?
As transaction volume and geographic coverage grow, features such as local acquiring, payment routing, fraud prevention, recurring payments, or marketplace functionality can become more important.
The best choice isn't necessarily the provider with the most features. Look for the capabilities that address the payment problems your business actually has.
What will you actually pay?
Don't compare providers using headline card rates alone. Look at your expected transaction mix, including domestic and international cards, local payment methods, currencies, average transaction value, and settlement requirements.
Ask providers for a worked example based on your expected volume. Check for payment-method-specific fees, FX charges, minimum invoices, subscriptions, and other costs that could affect your total cost.
Why Singapore businesses choose Airwallex
For businesses selling internationally, Airwallex is a strong option for managing payments across markets and sales channels. Here’s what you get with Airwallex:
Accept 160+ local payment methods in 180+ countries
Airwallex supports 160+ local payment methods across 180+ countries, including PayNow, GrabPay, Atome, Apple Pay, Google Pay, Alipay, and WeChat Pay. This gives businesses a way to offer locally familiar payment options as they expand into new markets.
Manage online and in-person payments together
Airwallex combines online payment acceptance with in-person payments through Airwallex POS. This gives businesses selling through both eCommerce and physical locations a single payment platform, rather than requiring separate systems for each channel.
Optimise conversion rates with Optimize 360
Optimize 360 uses multiple acquiring connections to route each payment through the option most likely to approve it. This improves authorisation rates, reduces failed payments, and helps you turn more international checkout attempts into successful sales.
Case study: Motherswork
Singapore-headquartered family retailer Motherswork moved from PayPal and a Stripe-based gateway to Airwallex.
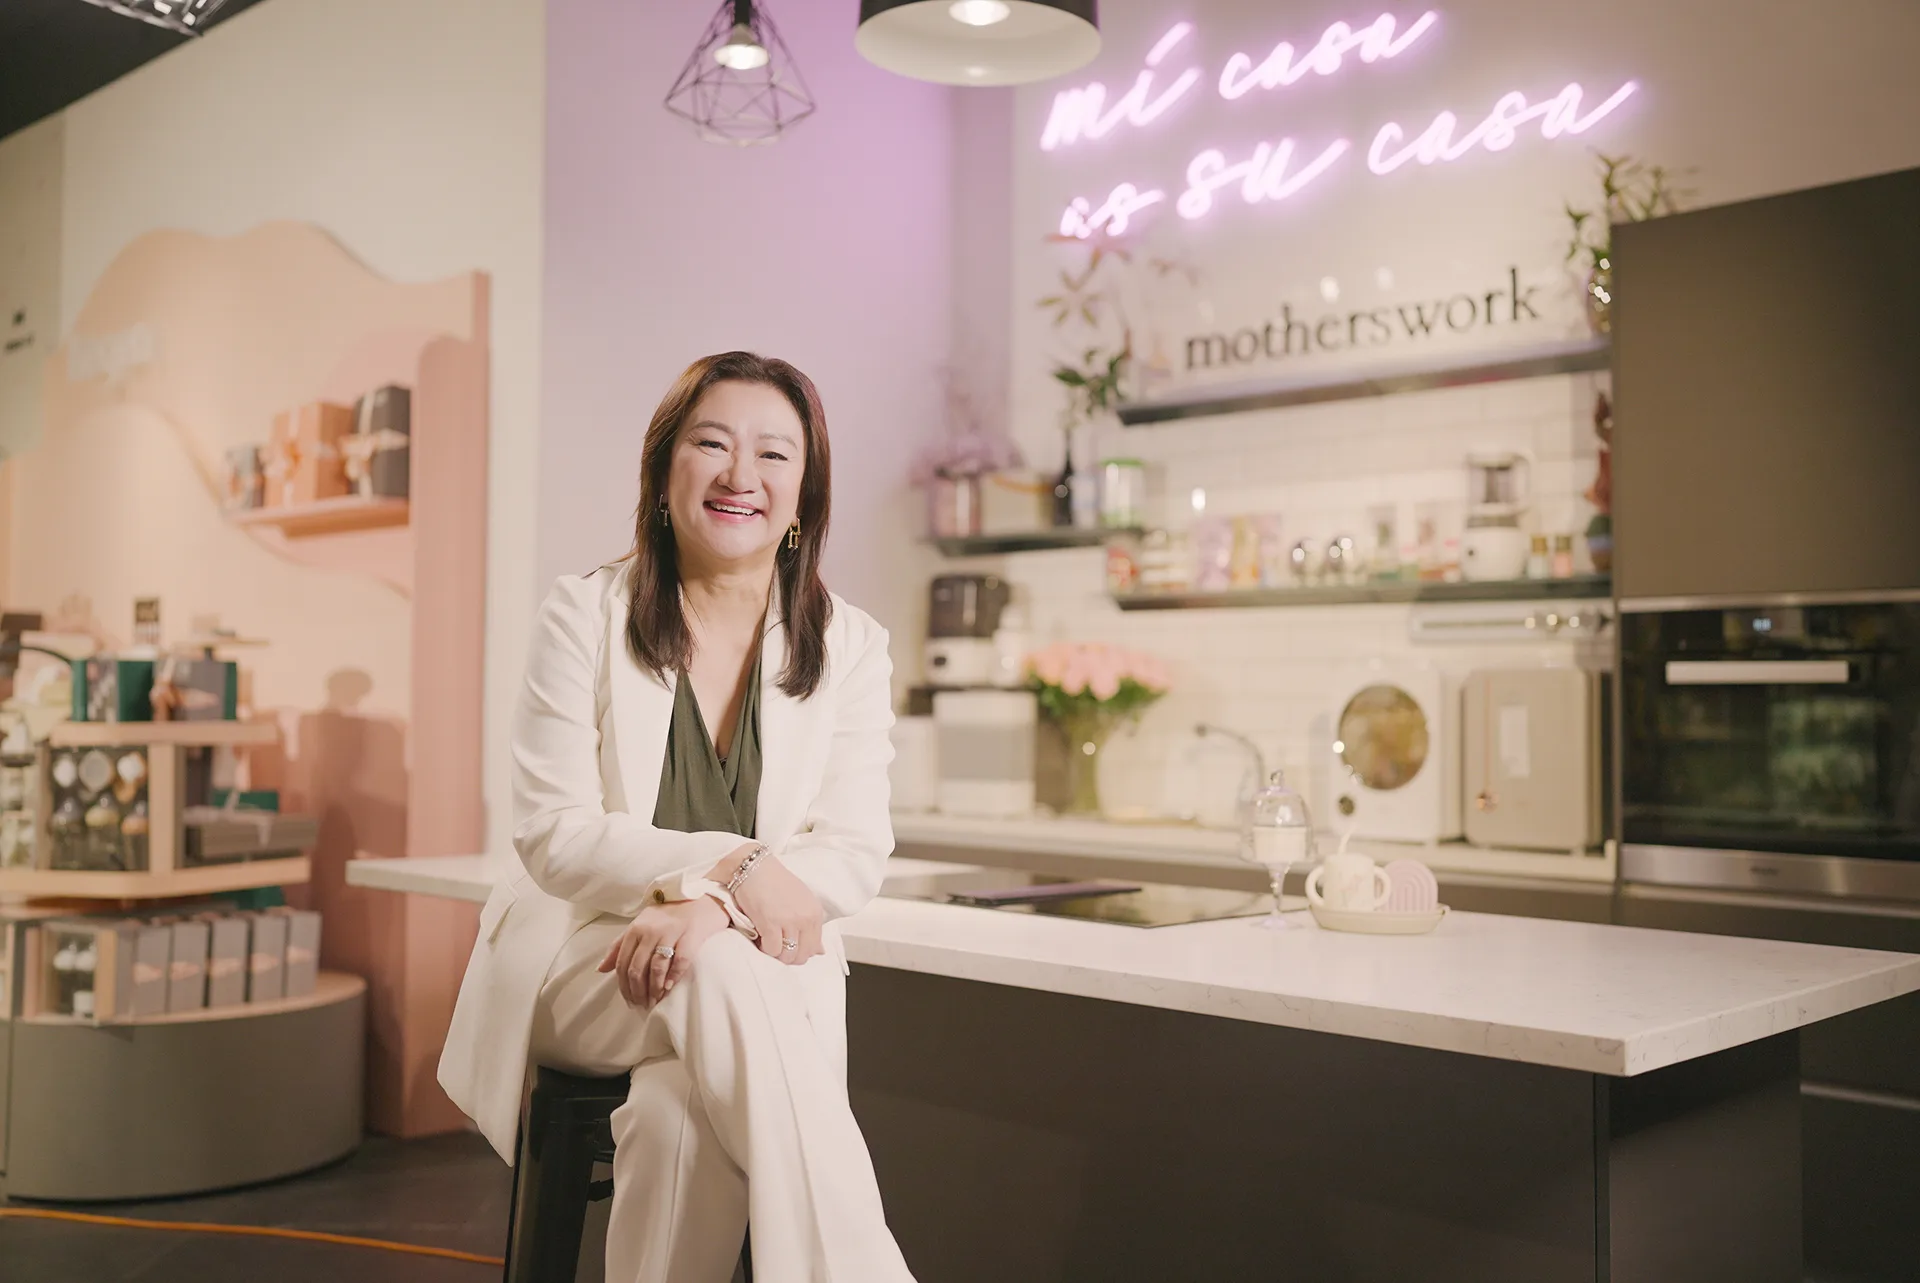
The results: 23% lower international transaction fees, a 29% lift in online conversion, a 4% increase in average order value, and roughly 95% of supplier transfers settling same-day.
Want to lower your transaction fees and improve online conversions like how Motherswork did?
Frequently asked questions (FAQs)
Which payment gateway is best in Singapore?
The best payment gateway depends on how you sell and where your customers are. Airwallex is a strong option for businesses that sell internationally or across both online and physical channels, with 160+ local payment methods, like-for-like settlement in 14 currencies, and Airwallex POS for in-person payments. Stripe is well suited to businesses that need highly customisable payment integrations, while Shopify Payments is a natural choice for merchants already using Shopify.
How much does a payment gateway cost in Singapore?
Most payment gateways in Singapore charge a percentage of each transaction, often with a fixed fee on top. For online card payments, published rates currently range from around 2.8% to 3.9%, plus a fixed fee of around S$0.30 to S$0.50. International cards can cost more, while currency conversion may add a separate FX fee. Local payment methods such as PayNow are generally cheaper, with published rates starting from around 0.65%.
What payment methods should my payment gateway support in Singapore?
At minimum, your gateway should support Visa, Mastercard, Amex, and PayNow, which are the dominant card networks and the most-used local payment method in Singapore. If you sell to consumers, add GrabPay, Apple Pay, and Google Pay. If you sell across SEA, you'll also want coverage for Atome, Alipay+, GCash, Dana, and ShopeePay depending on your target markets.
How long does settlement take with a Singapore payment gateway?
Settlement timelines vary by provider and payment method. Card payments typically settle in 2 to 7 business days, while PayNow can settle as quickly as T+1. PayPal settles to your PayPal balance instantly but requires a separate withdrawal step. Check each provider's stated settlement schedule, since longer timelines tie up working capital.
Can I use more than one payment gateway?
Yes, and many businesses do; for example, running one gateway for card acceptance and another for regional wallets. The trade-off is operational complexity: separate dashboards, separate reconciliation, and split customer data. A single platform that covers your full acceptance, settlement, and payout needs usually costs less in total once you account for the operational overhead.
Is a payment gateway the same as a payment processor?
No. A payment gateway captures customer payment details at checkout and securely passes them to the payment processor, which moves the funds between the customer's bank and your merchant account. Most modern providers including Airwallex bundle both functions into a single product, so you rarely buy them separately. You can read more about the difference between payment gateways and payment processors.
Sources:
https://www.paypal.com/sg/webapps/mpp/merchant-fees
https://stripe.com/en-sg/pricing, https://docs.stripe.com/payouts/multi-currency-settlement
https://www.adyen.com/pricing, https://docs.adyen.com/account/supported-currencies
https://www.shopify.com/sg/pricing
https://www.hitpayapp.com/sg/pricing
https://www.omise.co/en/pricing/singapore
This publication does not constitute legal, tax, or professional advice from Airwallex nor substitute seeking such advice, and makes no express or implied representations / warranties / guarantees regarding content accuracy, completeness, or currency. This publication is not intended to be relied on for the purpose of making a decision about a financial product and users should verify details independently. This advertisement has not been reviewed by MAS. It is for general information only.
All comparisons and information contained in this publication reflect only Airwallex’s own research using public documentation on the stated dates and have not been independently validated.
Product features, pricing and other details are subject to change. All third-party names, products, and logos are trademarks of their respective owners and are referred to for identification and compatibility purposes only. If you would like to request an update, feel free to contact us at [[email protected]].
Airwallex (Singapore) Pte. Ltd. (201626561Z) is licensed as a Major Payment Institution and regulated by the Monetary Authority of Singapore.
Cherie Foo
Growth Content Manager
Cherie is a Growth Content Manager at Airwallex, where she develops content for businesses in Singapore and across Southeast Asia. She focuses on turning complex topics like cross-border payments, business accounts, and spend management into clear, practical guides that help founders and finance teams make confident decisions.
Posted in:
Online payments

